Showing posts with label economics. Show all posts

Tuesday, March 10, 2009

China — An Economic Port in the Storm


There are plenty of other retailers that are jumping on the Chinese bandwagon:

* Barbie goes to China. Mattel opened its six-story House of Barbie in Shanghai, its first stand-alone store in China. "There's no reason why in five to 10 years, China shouldn't be the biggest market in the world for us," said Richard Dickson, Barbie's general manager.

* Chinese love Apple. Apple is opening a second store in Beijing. You know why? Apple's sales in China jumped by 49 percent in the last quarter.

* Door-to-door? No problem. Even multi-level marketer Amway is in China, where it increased its sales by 28 percent in 2008.

My point is pretty simple: You better take a long look at every stock in your portfolio and make sure that it has a well-defined and aggressive China strategy. For the next several decades, companies are going to fall into one of two categories: (1) companies that make a mountain of money from selling to China and (2) companies that get clobbered by their low-cost Chinese competitors.

Thursday, March 27, 2008

Review: A Malaysian Economic Agenda

http://www.keadilanrakyat.org/library/documents/mea.pdf

Our Parti Keadilan Rakyat (PKR) advisor, Datuk Seri Anwar Ibrahim wrote a compelling summary of Malaysia's economic status in a leaflet entitled A Malaysian Economic Agenda, As I See It. You can access it from the link above.

The couch potato, however, may read my summary. Among our economic woes he highlights are:

1. The NEP
... has produced upward social mobility for certain sub-sectors of the majority Bumiputeras
...creating a sub-class of Bumiputera professionals and engineering and urban Bumiputera middle class
...special Bumiputera shares, contracts and privatization deals that are channeled to well-connected parties
2. Worsening disparity
...worse income disparity gaps in Southeast Asia, behind even Indonesia and Thailand, as measured by it's GINI coefficient of 0.47
...second worse in all of the Asian countries...only Papua New Guinea ranks worse
...is a paradox...Malaysia is no longer an emerging economy or a third world nation in terms of development: in the United Nation's Development Programme's (UNDP) 2004 Human Development Report
...HDI score of 0.793...on the threshold of the UNDP's definition of a 'Highly Developed Country', which is a score of 0.800 or above
3. Poverty
...has not been mitigated.
...although...fall in absolute poverty levels in Malaysia from 29% in 1980 to 5-6% in 2000, the income threshold used to measure the poverty line is absurdly low...RM510
4. Corruption
...44th place among 163 countries surveyed on Transparency International's 2006 Corruption Perceptions...down from 39th position last year.
...annual survey...by the Hong Kong based Political and Economic Risk Consultancy (PERC)...Malaysia ranked 7th with a score of 6.25, worse than in 2006 when Malaysia scored 6.13
5. Protectionism and lost of competitiveness
...1997, before the crisis, Kuala Lumpur Stock Exchange ranked as the highest in Southeast Asia...in 2003, we ranked lower than Singapore and Thailand.
...FDI...plunged to US$3.87bil last year from US$4.62 bil in 2004
...bucked a generally rising trend. Overall FDIs to South, East and Southeast Asia reached a new high of US$65bil
...overtaken by Indonesia in the FDI stakes for the first time since 1990
...one of the reasons...other countries more transparent and offer greater ease in doing business...it takes 450 days and 31 procedures to enforce a contract in Malaysia, whereas it takes just 120 days and 29 procedures in Singapore.
6. Privatization policy failure
...PROTON is a struggling brand desperately looking for strategic alliances
...PERWAJA has failed spectacularly by running up liabilities of RM13 billion
Oh I like this:
we should not be persisting in the futile exercises of comparing ourselves with nascent economies like China and Vietnam...There is no pride in being the first among a bunch of mediocre competitors; instead we should aim to be the first among equals

He then goes on to compare Malaysia to Singapore citing a whole host of statistics which are to depressing to repeat. Further on, he gives suggestions, well-intentioned but rather abstract and lacking in practical plans, to solve our economy's problems.

I couldn't have said things better myself. However I don't agree that privatisation has brought only trouble. He suggests that 'there needs to be a reversal of policy from poorly-managed privatization to efficient and transparent public management for key sectors such as healthcare and transport.' Then he goes on to describe how PLUS has benefited only primary shareholders and private hospitals have increased both medical care and insurance charges.

Alamak. A reverse back to public responsibility of such would be tedious, slow, difficult, complicated and a whole waste of time and money. How come Anwar didn't consider introducing more competition? Perhaps the reason costs are so high and quality and delivery are so poor could be the monopoly hence the complacency of the sole company in the market? Maybe the market for healthcare an transportation could be an oligopoly instead. I mean, examine the mobile phone service providers. We're constantly getting cheaper rates and better deals while their profit's rising. See: http://www.telecomasia.net/article.php?id_article=7111 and http://www.mindbranch.com/Maxis-Communications-Bhd-R313-30508/. Oh but this is a H1 econs student's opinion.

I, for one, would like to see more of Anwar's opinion oh why he favors public control over more competition. What a pity it is difficult to find access to healthy debates and discussion online.
Given that Malaysia is predicted to become a net importer of oil by 2011 (http://thestar.com.my/news/story.asp?file=/2008/3/14/focus/20640241&sec=focus)
or at least before 2020
(http://www.peakoil.com/article5978.html , http://www.energybulletin.net/22213.html) ,
and that our country is heavily dependent on oil revenue
(federal government non-oil primary deficit estimated at 7 percent of GDP, source: http://www.imf.org/external/np/sec/pn/2006/pn0630.htm)
...the country's prospects aren't looking good for my generation.

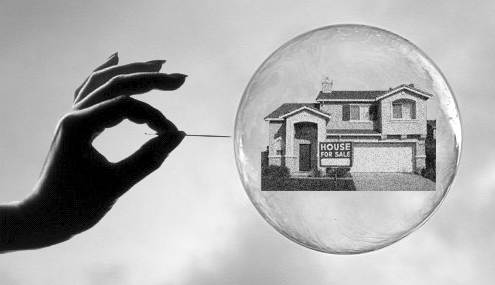
The US housing bubble and the subprime mortgage crisis for dummies.

We've all heard countless alarmist (or maybe not) news reports with the phrases 'sub-prime mortgage crisis' and 'housing market bubble burst' repeatedly appearing before us.

I remember once in Econs class, a classmate once asked the teacher if we needed to understand the current US housing market crisis in preparation for our exams. I distinctly remember being very relieved that we didn't have to. I'd have to face a whole new bunch of economics jargon: bubble, mortgage, equity...huh? Anyway it's now time for me to do some homework, for my enlightenment and yours.

Bubble:
An economic bubble happens when trade is at prices higher than intrinsic values. In the housing market bubble, there is an over-valuation of property. Because it is often difficult to observe intrinsic values in real-life markets, bubbles are often identified only in retrospect, when a sudden drop in prices appears. Such drop is known as a crash or a bubble burst.

How do bubbles happen?
The appreciation of real estate prices has lured many to become homeowners, in anticipation of future appreciation of their house/asset. This belief is fueled by the confidence is housing as a good investment as well as speculation of future rise in prices. Other reasons for the surge in buying include the mania for home ownership (Bush's 2004 campaign slogan: "the ownership society") and low interest rates (interest rates after 2001-2002 recession were at the all-time low 1% before they were subsequently raised in 2004-2006 to 5.25%) which then translates to cheaper and easier borrowing. This is also further aggravated by easy access to loans through subprime borrowing (explanation below).

Mortgage:
A loan to finance the purchase of real estate, usually with specified payment periods and interest rates. The borrower (mortgagor) gives the lender (mortgagee) a legal claim on the property as security/guarantee for the loan.

How do bubbles burst?
As a result, the appreciation of home values far exceeded the income growth of many of these homebuyers. When the Federal Reserve raised interest rates, the cost of borrowing became too costly, hence the demand for property fell. Thus prices of real estate begin crashing.

How the two are linked:
When the housing market bubble bursts, the values of their property plummeted due to a glut of housing supply in the market. As a result many owners now hold negative equity - the value of the asset used to secure a loan is less than the outstanding balance on the loan. This means the borrower will both have lost the property and still be in debt.

Subprime lending:
Defines lending to 'risky' borrowers, borrowers with compromised credit history. the risk for lenders is often offset by higher interest rates, ie rates above the prime rates.

The housing market crash caused many subprime borrowers to default on their loan and subprime lenders to file for bankruptcy. How do they get bankrupt? To put it simply, financial institutions, banks, earn their revenue from the higher interest rate they earn from loans they give. A default on the loan would mean the bank has lost not only its profits from the anticipated interest rate revenue but also lost the mean to pay back the debt 'borrowed' from savings account holders or other financial institutions.

From here on, many homeowners cut back spending, lose their jobs...bla bla bla..recession!
If you want to know more, wikipedia is a great place to start ( and to end also ;} )